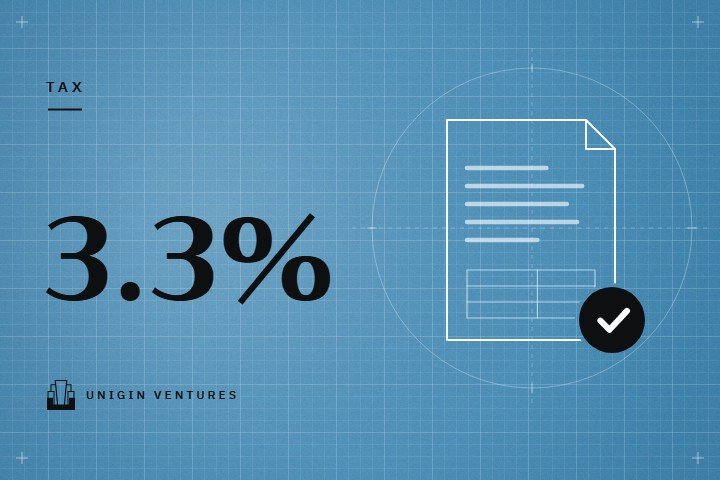
Cars and machinery carry VAT; land and buildings carry 3.3% specific business tax, 1% withholding and a transfer fee. The tax base for each, the gain on sale, and a worked example before you set a price.
Services performed in Thailand and used abroad can carry 0% VAT. The conditions, real Revenue Department rulings on what qualifies, a monthly VAT calculation, and what to put in contracts and invoices.
A 1.5% monthly surcharge, penalties of one or two times the tax and fines up to THB 2,000 apply differently to income tax and VAT, and to fixing errors yourself versus being caught. With a worked example.
Older and disabled employees' wages, staff training and e-Tax systems are deductible at twice the cost, but the saving depends on your tax bracket. Conditions, a worked example and deadlines.
Software, online ads and overseas consultants: who files PP 36 VAT, which payments need 15% PND 54 withholding, how tax treaties change the rate, and why net-of-tax contracts cost more.
Accounting profit and taxable profit differ. Follow the PND 50 form line by line: disallowed expenses, exempt dividends and five-year loss carryforwards, with a worked example and checks before you sign.
Section 82/5 and Notification No. 42 explained: passenger cars, abbreviated invoices and entertainment, which items stay tax-deductible, the invoice errors that cost the most, and a booking checklist.
From the first hire, Thai employers withhold salary tax on PND 1 and remit social security every month. How to calculate both, a four-person example, the new 875 baht cap, and the 7th and 15th.
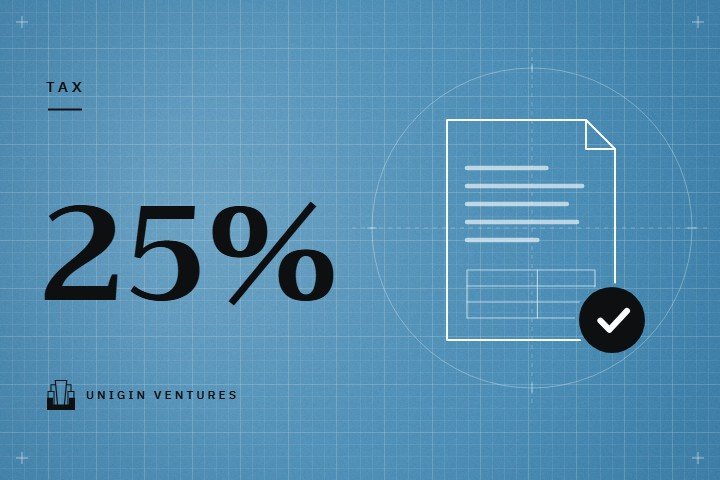
Thai SMEs pay half-year tax on half their estimated annual profit. Fall short by more than 25% and a 20% surcharge may apply. The calculation, the safe harbors and how to choose an estimate.
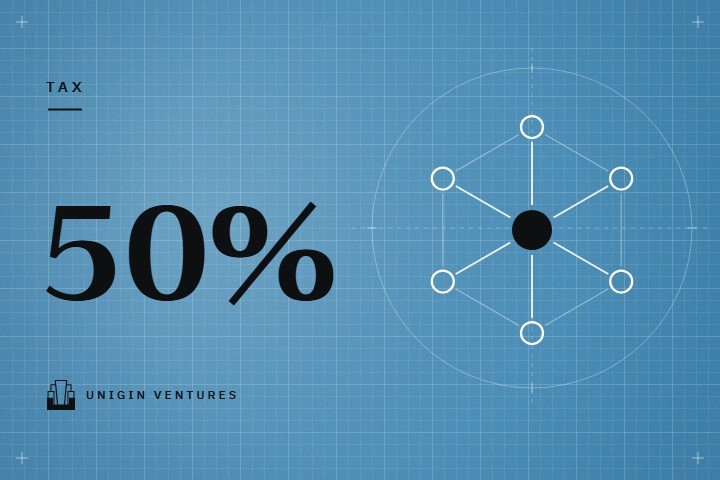
If one owner holds at least 50% of two companies, they are related. Who must file Thailand's transfer pricing disclosure form, the fines, the documents, and why small SMEs still need fair prices.
Companies pay 3.3% SBT on land sales however long they held it, interest on loans may be taxable, and unstamped contracts carry surcharges up to six times the duty. Rates, payers and checks.
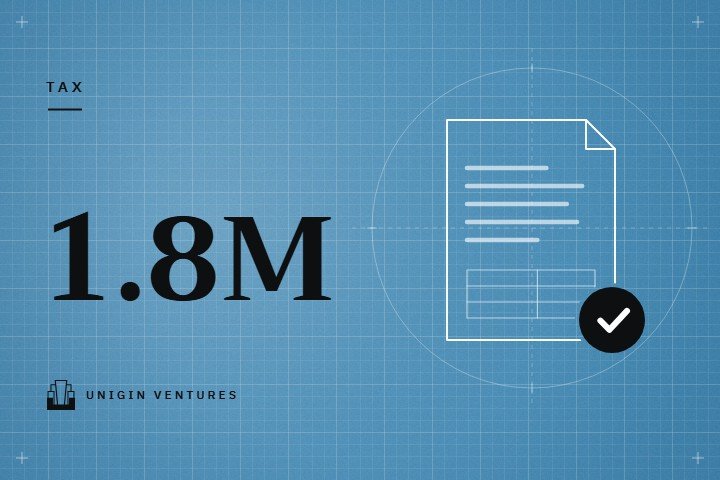
Book revenue on what customers paid, not on payouts. Measure the 1.8-million-baht VAT threshold correctly, claim input VAT on fees, and file P.P.36 for overseas ads, with a full-year example.
BOI promotion is not just for big factories. Thai SMEs can qualify from 500,000 baht of investment with a tax exemption cap of up to 200%. Here are the conditions, the SME efficiency measure and the obligations.
7 min read
Unigin Ventures
Building something worth backing?
Unigin Ventures invests in and supports startups and SMEs with capital and advice on finance, accounting, legal matters and technology.