Book revenue on what customers paid, not on payouts. Measure the 1.8-million-baht VAT threshold correctly, claim input VAT on fees, and file P.P.36 for overseas ads, with a full-year example.
How to build scenarios in one spreadsheet: pick the drivers that move cash, calculate year-end cash in four cases, set a cash floor, and agree on triggers and actions in advance.
How to count MRR without one-off items, build a five-part MRR bridge, measure churn three ways, and read a cohort table to see if newer customers stay longer, with a worked example.
What to capitalize, how depreciation works under TFRS for NPAEs, the maximum tax rates in Royal Decree 145, and why a 1.5 million baht passenger car is never fully deductible.
A Thai limited company cannot hold its own shares or issue below par, so how do you give employees equity? Workable structures, vesting terms, Section 40(1) tax and how the option pool affects founders.
BOI promotion is not just for big factories. Thai SMEs can qualify from 500,000 baht of investment with a tax exemption cap of up to 200%. Here are the conditions, the SME efficiency measure and the obligations.
Customers pay in 60 to 90 days, but your bills can't wait. How factoring works, recourse versus non-recourse, converting fees into an annual rate, and what to check before you assign invoices.
How risky is it when one customer brings in nearly half your revenue? Measure it with three numbers, test your profit if that customer leaves, and close the gaps in contracts and receivables.
Revenue arises when you deliver, not when you bill or get paid. The TFRS for NPAEs rules, worked examples of deferred revenue and stage of completion, where VAT timing differs from the books, and month-end adjustments.
How pre-money, post-money and ownership fit together, the venture capital method with a worked example, the Berkus and Scorecard methods for pre-revenue companies, and why the highest valuation isn't always the best offer.
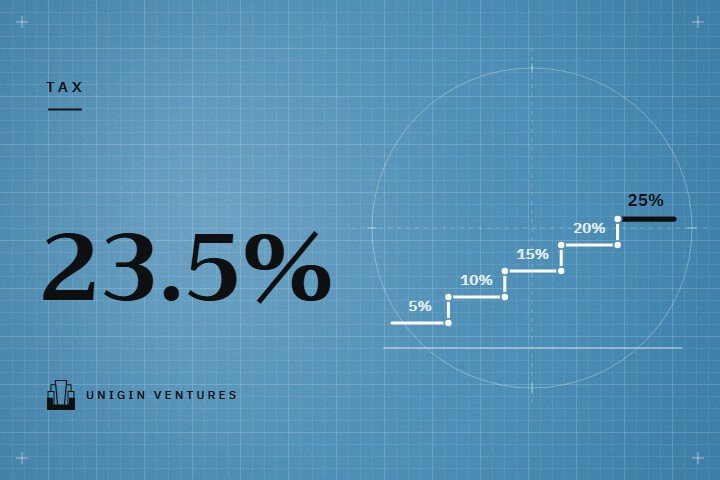
Compare the combined tax on company and owner when you take salary, dividends or a mix. See the 23.5% crossover point, a worked example, and the legal conditions for paying dividends.
An annual budget sets targets and approves spending. A rolling forecast always looks 12 months ahead. How they differ, how to build one from a few drivers, and what it shows when sales miss plan.
7 min read
Unigin Ventures
Building something worth backing?
Unigin Ventures invests in and supports startups and SMEs with capital and advice on finance, accounting, legal matters and technology.