Thai Withholding Tax for SMEs: Common Rates, Forms and the 1% e-Withholding Rate
Withholding rates on rent, services, professional fees, advertising and transport, when to use PND 3 or PND 53, online filing deadlines, common mistakes, and the 1% e-withholding rate through 2027.
In this article
Every time a company pays rent, a service fee or an advertising bill, the accounting team faces the same questions: what percentage to withhold, which form to file, and by when. Getting it wrong doesn't only affect the person being paid. Thai law makes the payer jointly liable.
This article pulls together the withholding tax rates SMEs use most, the forms and deadlines, a one-month worked example, the most common mistakes, and payment through the e-Withholding Tax system, which cuts the rate to 1%.
What withholding tax is and who must withhold
Withholding tax is an advance collection of the recipient's income tax. The payer holds back part of the payment and remits it to the Revenue Department on the recipient's behalf. The recipient then credits the amount against their tax for the year. It is not an extra cost to the payer, but it is a duty the payer has to get right.
- For rent, services, contract work, advertising and transport, the duty falls on the paying company, juristic partnership or other juristic person.
- Withholding applies when payments under a single contract total 1,000 baht or more.
- The payer must issue a withholding tax certificate (commonly called a "50 Tawi") to the recipient, and keep a special register of amounts withheld and remitted.
The rates SMEs use most
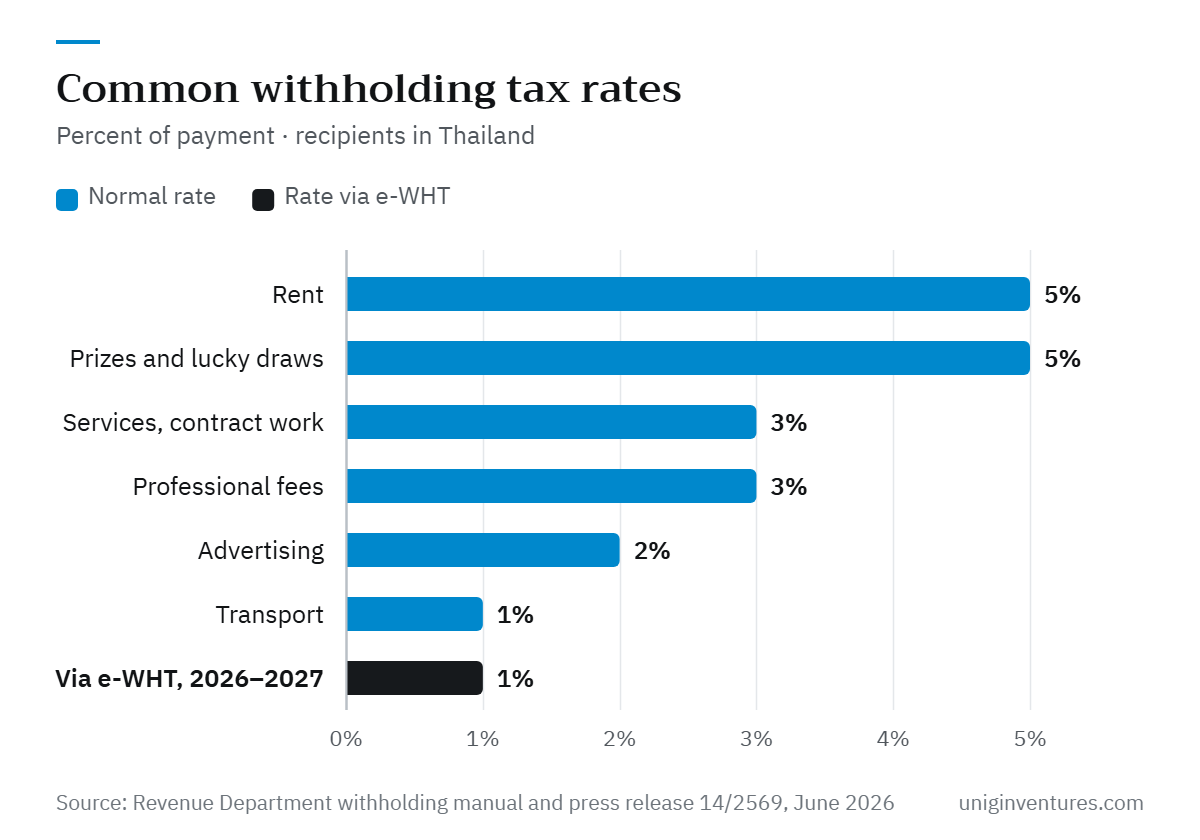
Rates under Revenue Department Order Tor Por 4/2528, for recipients in Thailand:
| Type of payment | Paid to an individual (PND 3) | Paid to a company (PND 53) |
|---|---|---|
| Rent on buildings, houses and other property | 5% | 5% |
| Professional fees (law, accounting, engineering, architecture, medicine, fine arts) | 3% | 3% |
| Contract work and construction contracts | 3% | 3% |
| Other services | 3% | 3% |
| Advertising | 2% | 2% |
| Transport (excluding public transport fares) | 1% | 1% |
| Prizes from contests, competitions and lucky draws | 5% | 5% |
Within "other services," hotel charges, restaurant bills, life insurance premiums and public transport fares are not subject to withholding. Ordinary purchases of goods are not among the income types the Revenue Department's manual lists for withholding. Payments to recipients abroad have their own rates and form (PND 54), so check those case by case with your accountant.
Forms and deadlines
- PND 1 for salaries and wages paid to employees
- PND 3 for payments to individuals, such as rent to a private landlord or fees to a freelancer
- PND 53 for payments to companies and juristic partnerships
By law, returns and tax are due within 7 days of the end of the month in which the payment was made. The Ministry of Finance extends this by 8 days for online filing, to 15 days after month-end, for returns due between February 1, 2024 and January 31, 2027.
One thing has already changed. Revenue Department Notification on Income Tax No. 451 requires withholding tax returns, including PND 1, PND 3 and PND 53, to be filed electronically for payments made on or after January 1, 2025. Payers who cannot file electronically must submit a letter explaining why, together with the return, at their area revenue branch office.
A one-month worked example
Illustrative example: a company makes the following payments in one month (amounts before VAT).
| Payment | Amount (baht) | Form | Normal rate | Tax withheld (baht) | Via e-WHT (baht) |
|---|---|---|---|---|---|
| Office rent, individual landlord | 30,000 | PND 3 | 5% | 1,500 | 300 |
| Design work, freelancer | 20,000 | PND 3 | 3% | 600 | 200 |
| Bookkeeping, accounting firm (company) | 15,000 | PND 53 | 3% | 450 | 150 |
| Advertising, agency (company) | 50,000 | PND 53 | 2% | 1,000 | 500 |
| Freight, transport company | 8,000 | PND 53 | 1% | 80 | 80 |
| Total | 123,000 | 3,630 | 1,230 |
Paying the usual way, the company files PND 3 for 2,100 baht and PND 53 for 1,530 baht by the 15th of the following month, and issues certificates to all five recipients. Paying through e-Withholding Tax, total withholding falls to 1,230 baht, and the five recipients receive 2,400 baht more in cash that month. Freight doesn't change because its normal rate is already 1%.
e-Withholding Tax: withholding through the bank at 1%
e-Withholding Tax means paying through a bank that participates in the Revenue Department's program. The payer enters the withholding details when making the transfer, and the bank withholds the tax and sends the data and the tax to the Revenue Department. Both payer and recipient can check the records in the Revenue Department's system, where the department says data appears within 6 business days of the transaction.
- The rate drops to 1% for income normally withheld at 5%, 3% or 2% when paid through e-Withholding Tax. The first round of the measure covered payments from January 1, 2023 to December 31, 2025.
- On June 16, 2026, the cabinet approved extending the measure from January 1, 2026 to December 31, 2027, according to Revenue Department press release 14/2569. The extension has to be issued as a ministerial regulation, so confirm with your accountant that it has been published in the Royal Gazette before applying the rate.
- Companies that invest in or pay service fees for e-Withholding Tax and e-Tax Invoice & e-Receipt systems can deduct twice the actual cost over the same period.
Who benefits most? Recipients get more cash immediately because less is withheld. Payers gain on paperwork. A company that pays rent or uses many small service providers can also use e-Withholding Tax as a bargaining point, since smaller recipients usually prefer to receive more of their money up front.
Common mistakes
- Not withholding, or withholding too little. The payer becomes jointly liable with the recipient for the tax not withheld or the shortfall, under Section 54 of the Revenue Code.
- Remitting late. A surcharge of 1.5% per month or part of a month applies to the tax due. Deliberately failing to file in order to evade tax carries a fine of up to 5,000 baht, up to six months in prison, or both, under Section 37 bis.
- Absorbing the tax but calculating it on the original amount. If you agree that the recipient gets the full fee and the company bears the tax, the tax you pay on their behalf also counts as their income, so the withholding has to be grossed up rather than calculated on the original amount alone.
- Using the wrong form. Individuals go on PND 3, companies on PND 53. Check the recipient's company certificate or tax ID rather than guessing from a shop name.
- Splitting invoices to stay under 1,000 baht. The threshold applies per contract. If a single contract is paid in several installments that total more than 1,000 baht, withholding still applies.
- Losing track of certificates for tax withheld from you. When customers withhold from your company, their certificates are your evidence for the tax credit on your PND 50 corporate return. Collect them every month rather than chasing them at year-end.
Where to start
- Pull last month's payments, group them by the categories in the rate table, and separate individual recipients from companies.
- Map each expense code in your accounting system to its withholding rate so no one has to decide afresh at every payment.
- Make sure you have a Revenue Department e-filing account, and set a reminder to file PND 3 and PND 53 by the 15th of every month.
- Ask your bank whether it offers e-Withholding Tax, and try it first with rent or a regular service provider.
- Keep a register of withholding certificates received from customers, so you can claim the credit on your corporate income tax return.
Withholding tax isn't complicated, but it happens every time money goes out, so small mistakes add up to surcharges and shared liability. Linking rates to expense types from the start, and moving payments onto e-Withholding Tax, cuts both the paperwork and the risk.
Sources
- Withholding tax manual for PND 3 and PND 53 filers — Revenue Department (in Thai)
- Revenue Department Order Tor Por 4/2528 — Revenue Department (in Thai)
- Ministry of Finance notification extending online filing deadlines (No. 7, as amended by No. 8) — Revenue Department (in Thai)
- Withholding Tax (WHT) system — Revenue Department (in Thai)
- Press release 14/2569: extension of electronic tax system incentives — Revenue Department (in Thai)
- Withholding Tax 2023 seminar (reduced rates for e-WHT) — Large Business Tax Administration Division 1, Revenue Department (in Thai)
- Withholding tax done right (tax borne by the payer counts as income) — Revenue Department (in Thai)